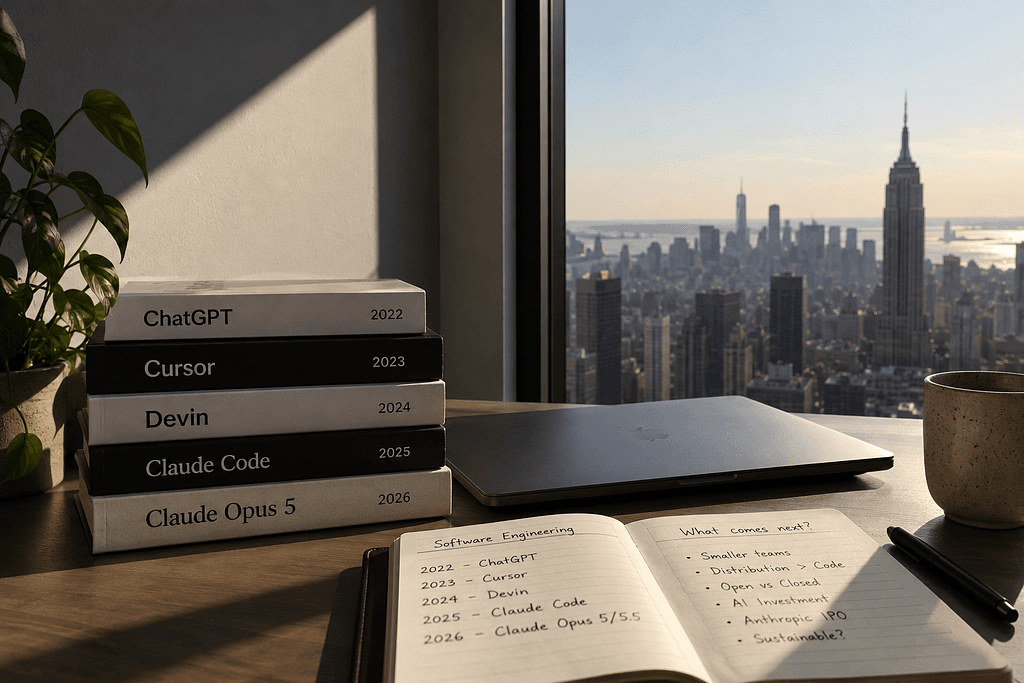
I still remember when Devin was unveiled on YT in March 2024. It was one of the first to show a vision where software engineers would become obsolete. My colleagues and friends were shocked, skeptical, and strangely relieved when the reality didn’t match the hype.
In 2022, the ChatGPT website came out, which could generate code snippets. Then came Cursor in 2023, integrating AI directly into the development environment, making us more productive.
Then Claude Code arrived in February 2025, allowing AI to execute entire development workflows.
The consensus remained that junior developers might struggle, but senior engineers were safe. After all, AI couldn’t replace years of architectural experience and engineering judgment.
Then came 2026.
Claude Opus 5 in July, followed by Opus 5.5 in September, pushed the ceiling significantly higher. Even experienced developers grew apprehensive about their job security amid widespread tech layoffs.
Suddenly, 50-person engineering teams began to shrink to just 5–10 people, forming small teams of independent contributors (ICs) as features that once took months to develop are now delivered in days. Now, simply building SAAS is no longer a moat. Distribution, proprietary data, customer relationships, and switching costs are becoming more valuable than the code itself.
But who actually wins this AI race?
Anthropic looks strong with Claude Code, but Google, OpenAI, and other startups in this niche remain competitors.
And there’s another battle: open-source vs. closed-source models.
DeepSeek, Qwen, Kimi, LiquidAI, and Google’s Gemma are making increasingly capable open-weight models accessible. While proprietary models continue pushing the frontier, open models are challenging them on cost, customization, and deployment flexibility.
Despite all this, the fear that the bubble will burst still looms.
Investors are increasingly scrutinizing whether the revenue generated by AI will justify these massive investments. It seems like investors are not willing to invest behemoth amounts of liquid cash anymore; everyone wants to take out their profits.
One example is CoreWeave. In October 2026, the market yield on some of its bonds maturing in 2031 briefly exceeded 16%.
A company operating in one of the most strategically important sectors of the decade saw its borrowing costs reflect significant investor concern.
It raises uncomfortable questions about how sustainable this investment cycle really is.
Software is becoming easier to build, engineering teams could become smaller, open models are challenging closed models, and the companies driving all this are spending extraordinary amounts of money.
So much has changed in just 4 years, yet the outlook feels increasingly uncertain. It looks like Anthropic’s IPO is the critical inflection point.


